How Insurance Works in Poland • KNF, UFG & Your Rights as a Driver
Poland Car Insurance Check: How to Verify OC by Plate, and How the System Protects You
Were you just in a collision, are you about to buy a used car, or have you received a letter from UFG? You can check whether any Polish-registered vehicle has valid OC (mandatory third-party liability) insurance in about a minute. All you need is the licence plate number and a date.
This guide starts with the practical part: a step-by-step UFG plate check. After that, it explains who stands behind your policy (KNF, UFG, the Financial Ombudsman) and what your rights are as a driver in Poland.
How to Check Polish Car Insurance by Plate (UFG Step by Step)
The Insurance Guarantee Fund (UFG, Ubezpieczeniowy Fundusz Gwarancyjny) keeps the central database of every OC policy sold in Poland. Every insurer must report its policies to UFG. That makes this the most reliable place to confirm whether a car was insured on a given day.
Step 1: Open the UFG website
Go to ufg.pl. The tool is free and does not require an account. It works on a phone, so you can use it at the scene of an accident.
Step 2: Choose the OC database tool
Select the "Baza OC i AC" (OC and AC Database) tab, then "Identyfikacja umowy OC na dzień" (Identify an OC agreement on a specific day).
Step 3: Enter the plate number and date
Type the registration number (numer rejestracyjny) exactly as it appears on the plate, without spaces. Then enter the date you want to check. After an accident, use the date of the incident. When buying a car, use today's date. If you don't know the plate, the form also accepts the VIN.
Step 4: Read the result
-
Policy found: You will see the insurer's name (for example PZU, Warta, Ergo Hestia, Allianz or Link4) and the policy number. That is everything you need to file a claim against the at-fault driver's OC.
-
No policy found: Either the vehicle was uninsured on that date, or the policy has not yet been reported to the database. Take photos, write down the other driver's details and call the police. In the case of an uninsured driver, the claim goes directly to UFG.
This check means you don't have to rely on the other driver's word. If they claim to be insured but can't show a document, you can verify it on the spot. For what to do next, see our walkthrough: Car Accident in Poland? File an OC Claim in 7 Steps.
Foreign plates: The UFG database covers vehicles registered in Poland. A car should be insured in its country of registration, so a German- or Ukrainian-plated car carries a policy from that country (or a Green Card). Polish OC does not apply to it. Zgodnie z ustawą o ubezpieczeniach obowiązkowych (under the Polish Compulsory Insurance Act), a Polish OC policy used abroad gives the level of cover required by the country where the accident happened or by the Polish act, whichever is broader.
More Checks Before You Buy a Used Car
Check the OC expiration date on historiapojazdu.gov.pl
The government site historiapojazdu.gov.pl shows whether a vehicle's OC is currently valid and when it expires.
-
Prepare three details from the registration certificate (dowód rejestracyjny): the registration number, the VIN and the date of first registration.
-
Open the "Oś czasu" (Timeline) tab.
-
At the bottom you will see a green bar if the policy is valid, plus its exact expiration date. You can also see whether the technical inspection (przegląd techniczny, the Polish MOT) is valid.
Check the full vehicle history on UFG Historia Pojazdu
The UFG Historia Pojazdu service at historiapojazdu.ufg.pl works as a background check for the car itself. Enter the registration number and VIN, complete the CAPTCHA and click "Sprawdź". The report shows three things:
-
Insurance history: all OC and AC policies for the vehicle, with any gaps in cover.
-
Claims history: how many claims (szkody) were reported, under which type of insurance, and roughly when. Suppose the seller says the car was "never in an accident" but the report shows three OC claims. That is a reason to dig deeper.
-
Mileage readings: odometer values recorded at insurance events. These are one of the best defences against odometer fraud (cofanie licznika).
Pro tip: Run the report before you visit the car. If the seller refuses to share the plate and VIN, treat that as a red flag. The basic report is free. The paid Raport Szczegółowy adds more data and is worth the fee for expensive vehicles.
UFG vs. gov.pl: what's the difference?
| Feature | UFG OC check (ufg.pl) | UFG Historia Pojazdu | historiapojazdu.gov.pl |
|---|---|---|---|
| OC on a specific date + insurer name | ✅ Yes | ✅ Yes (history) | ✅ Current status only |
| Claims history | ❌ No | ✅ Number, type, dates | ❌ No |
| Mileage readings | ❌ No | ✅ From insurance events | ✅ From inspections |
| Inspection (MOT) status | ❌ No | ❌ No | ✅ Yes |
| Data needed | Plate (or VIN) + date | Plate + VIN | Plate + VIN + first registration date |
| Cost | Free | Basic free, detailed paid | Free |
Best practice: Use all three. Together they give you the full picture before you sign anything.
When you buy a used car, the seller's OC policy transfers to you automatically, but only until its original expiration date. After that, you need your own policy. The seller has their own duties too, covered in our guide to selling a car in Poland as a foreigner.
Buying Your Own OC as a Foreigner: What to Expect
Many drivers who search for "poland car insurance check" soon need a policy of their own. If you are a foreigner, here is how the process works in practice.
-
Documents: To calculate an offer, we need three things:
- a photo of your passport or the national ID document from your country of citizenship,
- the vehicle purchase contract,
- a Polish address.
-
PESEL matters: Foreigners without a PESEL number receive far fewer offers. Without it, insurers cannot retrieve your Polish insurance history.
-
Price factors: Many factors affect the premium, including:
- the owner's age,
- your address,
- the car's make, model and engine capacity.
This is why quotes vary so much between insurers.
-
Term and payment: OC is bought for one year, and paying in instalments is possible. Payment is almost always made upfront by bank transfer.
-
Paying from a foreign account: A transfer from a foreign account can take up to several days, and you should allow for currency conversion costs. The policy is issued only once the payment has been credited to the bank account. Sending a transfer confirmation is not enough.
Timing at the registration office: Registration office (wydział komunikacji) websites often say the car must already be insured when you register it. That is not strictly true. However, the vehicle must be insured no later than the day of registration, before it is driven on the road. Because of the payment delays above, don't leave it until the last minute. See our guides on registering a car in Poland as a foreigner and how to buy car insurance in Poland.
UFG: Your Airbag and the Virtual Patrol
What if the person who hit you drives away, or never bought mandatory OC insurance? You are not left on your own. UFG works on two tracks.
-
As a guarantor: If an uninsured or unidentified driver causes damage, UFG pays the victim. This covers both vehicle damage and personal injury. UFG then recovers the money from the uninsured perpetrator through a recourse claim (regres), which can reach hundreds of thousands of złoty. UFG also steps in when an insurer goes bankrupt, so policyholders are not left without protection.
-
As a virtual patrol: By comparing the vehicle register with its policy database, UFG detects gaps in OC without any roadside check. For a missing OC, UFG charges a one-off penalty fee. The amount depends on how long the gap lasted, in three brackets:
- up to 3 days,
- 4–14 days,
- over 14 days.
The full rate for a passenger car is twice the national minimum wage: PLN 9,332 in 2025 and PLN 9,610 in 2026. The shorter brackets are a percentage of that amount. For details, read OC insurance penalties in Poland.
Why Does One Insurer Have Two Names?
Big companies such as PZU, Warta or Allianz often operate two separate entities under the same logo. This is a legal requirement: money from life insurance cannot be mixed with money from car or home insurance.
-
Division I (Life): Cover for people, such as death, illness or saving for retirement.
-
Division II (Property/Non-Life): Cover for things and liability, such as cars (OC/AC), homes, businesses and travel.
Because of this split, the funds of life insurance clients stay safe even if a disaster hits the property sector, such as a massive flood.
KNF: The Market Sheriff
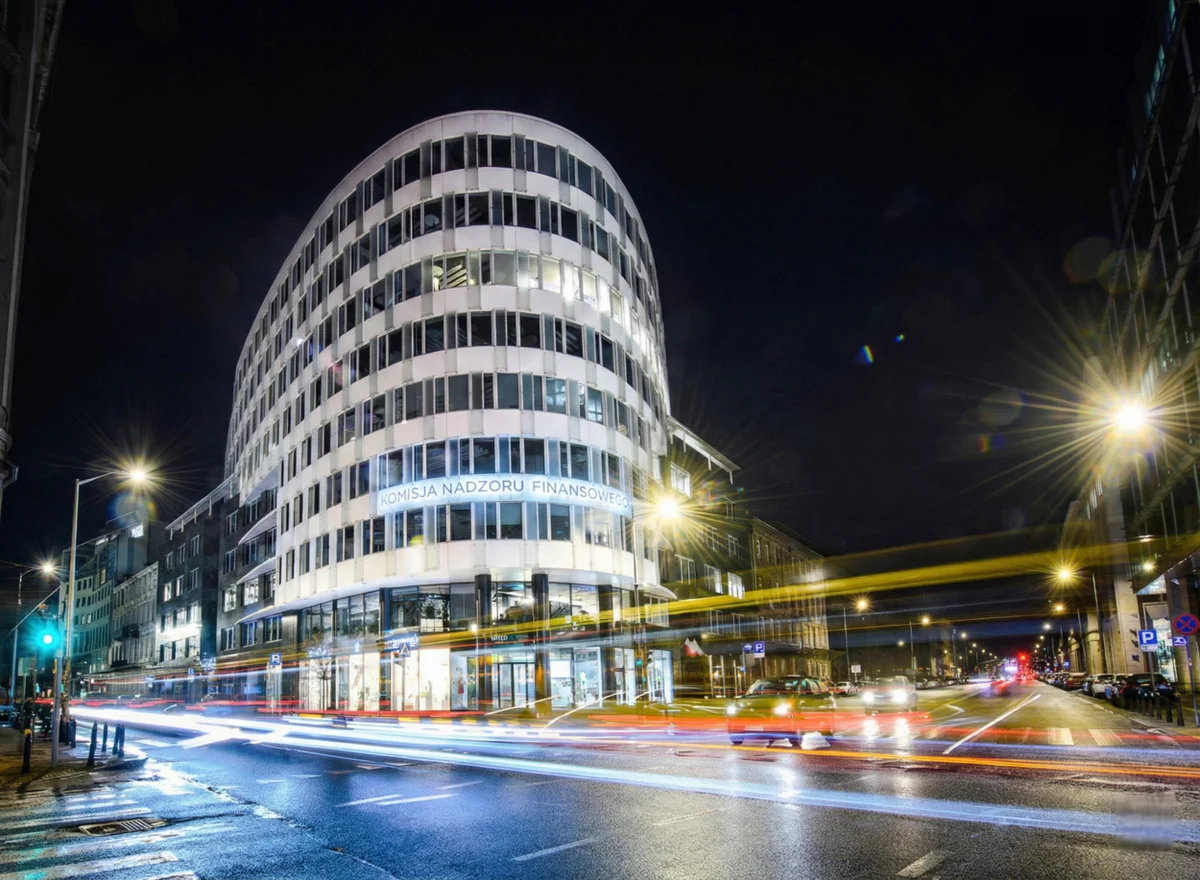
Insurance is a promise: "you pay today, we help you someday." The Polish Financial Supervision Authority (KNF, Komisja Nadzoru Finansowego) makes sure that promise is backed by real money. KNF licenses insurers and constantly examines their books. If a company's finances start to wobble, KNF doesn't wait for a collapse. It can impose a recovery plan or even take over management.
For anyone buying car insurance in Poland, this means every insurer on the market must meet the same solvency requirements. That applies to PZU, Warta and Ergo Hestia just as much as to a smaller company.
KNF reforms: strengthening independence
New legislation introduced a cooling-off period for senior KNF officials. After leaving the authority, they cannot take positions at the financial institutions they supervised. For consumers, this means the "sheriff" is harder to influence.
The DallBogg case: KNF oversight in action
DallBogg, a Bulgarian insurer, sold OC motor policies in Poland under EU freedom-of-services rules. KNF raised serious concerns about its claims handling and financial stability, and ultimately banned DallBogg from selling new OC policies in Poland. Drivers holding its policies were left in an uncertain position. It is a cautionary tale about choosing an insurer on price alone. If you bought a DallBogg policy, run the UFG check above and contact us to review your cover.
Who Is on Your Side?
-
Polish Chamber of Insurance (PIU, Polska Izba Ubezpieczeń): The insurers' industry body. It lobbies on legislation and publishes useful market statistics.
-
Financial Ombudsman (Rzecznik Finansowy): Your defender. If an insurer undervalues your compensation or refuses to pay, and your complaints go nowhere, the Ombudsman offers legal support and mediation. Filing a complaint is free.
What About AC and Other Voluntary Cover?
OC only pays for damage you cause to others. AC (Autocasco) insurance covers your own car against theft, vandalism, weather and at-fault collisions. It is voluntary, but practically essential for newer or financed vehicles. You can add NNW personal accident cover for the driver and passengers. The same KNF rules and consumer protections apply to all of these.
Frequently Asked Questions
How do I check Polish car insurance by plate number?
Go to ufg.pl, open "Baza OC i AC" and then "Identyfikacja umowy OC na dzień". Enter the registration number and a date. If a policy existed on that day, the system shows the insurer's name and policy number. To see the current expiry date, use historiapojazdu.gov.pl with the plate, VIN and date of first registration.
What is UFG in Poland?
UFG (Ubezpieczeniowy Fundusz Gwarancyjny) is the Insurance Guarantee Fund. It compensates victims when the at-fault driver is uninsured or unidentified, then recovers the money from the uninsured driver. It also keeps Poland's central OC database and charges penalty fees for gaps in OC.
What is KNF and why does it matter for insurance?
KNF (Komisja Nadzoru Finansowego) is the Polish Financial Supervision Authority. It licenses insurers, monitors their finances and enforces solvency rules. This ensures your insurer has the reserves to pay claims.
What happens if I drive without OC insurance in Poland?
UFG detects the gap automatically and charges a one-off penalty fee. The amount depends on the length of the gap: up to 3 days, 4–14 days, or over 14 days. The full rate for a passenger car is PLN 9,332 in 2025 and PLN 9,610 in 2026. If you cause an accident while uninsured, UFG pays the victim and then claims the full amount back from you.
The Bottom Line
A Poland car insurance check takes a minute on ufg.pl. Pair it with historiapojazdu.gov.pl and UFG Historia Pojazdu before buying any used car. Behind these tools is a well-organised system:
- separate life and non-life divisions,
- a strict supervisor (KNF),
- a guarantee fund and database (UFG),
- a consumer defender (the Financial Ombudsman).
Need OC for a newly bought car? Magro Ubezpieczenia has helped drivers in Łódź and across Poland for over 30 years. Send us your ID, purchase contract and Polish address, and we will compare offers from multiple insurers for you. Get a free quote and we'll walk you through everything, in English.